Under Section 391 of Manitoba’s Insurance Act, anyone who represents themselves as an insurance agent, broker, or adjuster without actually holding a valid license is committing an offence, not just breaching some industry norm. Most Winnipeggers buying a policy never check whether the person selling it to them is actually licensed at all, simply trusting a friendly manner, a professional-looking office, or a referral from a friend. The Insurance Council of Manitoba runs a free, public search tool specifically so that trust doesn’t have to be blind, and using it takes about as long as it took to read this paragraph.
- Checking a Broker’s License Takes Two Minutes and Most People Never Do It
- What the ICM Search Actually Tells You
- Wawanesa: Winnipeg’s Own National Insurer
- Red River Mutual: Manitoba-Rooted, Broker-Distributed
- Mutual vs Stock Companies, and Why It’s Worth Knowing
- Direct Writers vs Broker-Distributed Insurers
- National Insurers With a Real Winnipeg Presence
- Finding the Right Broker for Your Specific Coverage
- Common Questions
- Verify Before You Sign Anything
Winnipeg’s insurance market includes Wawanesa, a Canadian mutual insurer with its executive office right in downtown Winnipeg, Red River Mutual, an Altona-based company with deep Manitoba roots and a Winnipeg regional office, and a wide network of national insurers and independent brokers operating across the city. Before working with any of them, the Insurance Council of Manitoba’s public licence search lets you confirm exactly who you’re dealing with, what they’re licensed to sell, and whether their license carries any conditions worth knowing about upfront.
Checking a Broker’s License Takes Two Minutes and Most People Never Do It
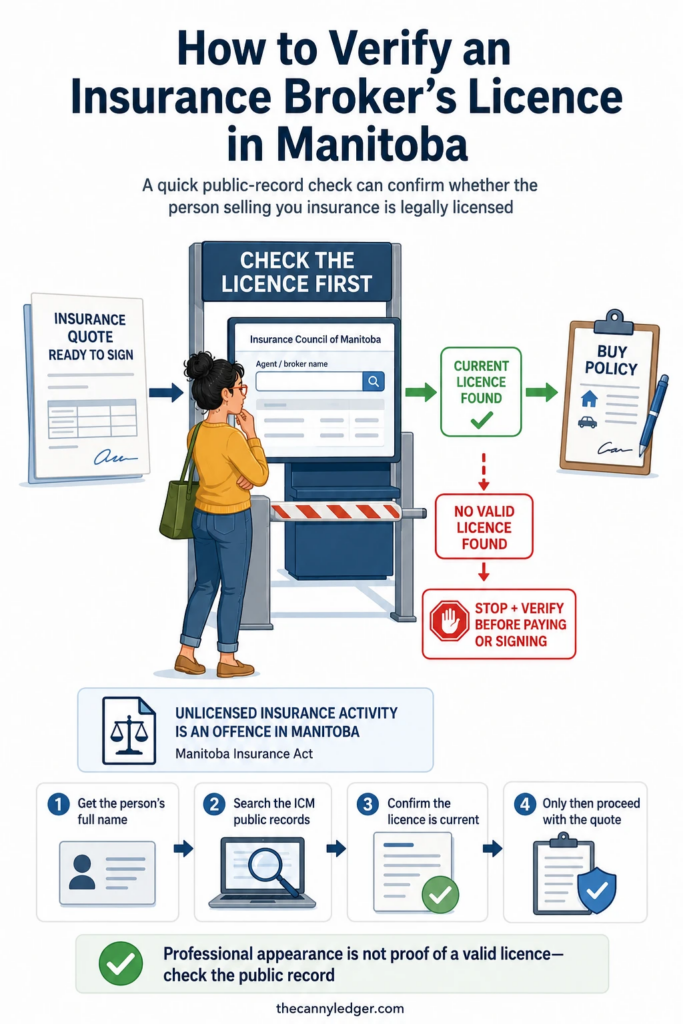
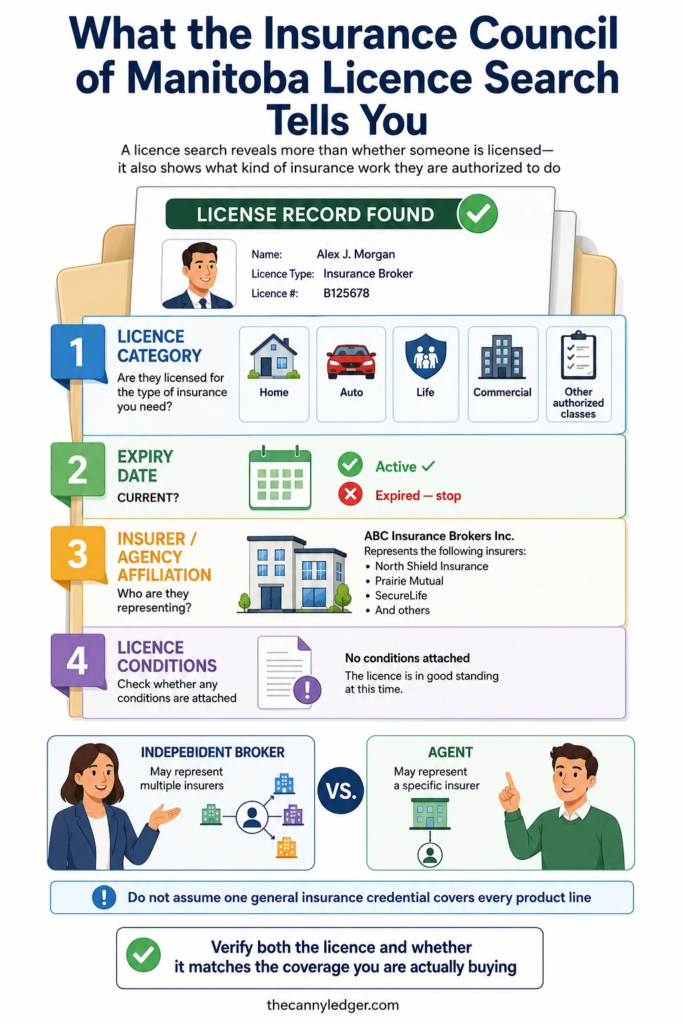
The Insurance Council of Manitoba is the regulatory body responsible for licensing and disciplining every insurance agent, broker, and independent adjuster operating in this province, and it maintains a public search tool specifically built for consumers to verify who they’re working with before money changes hands. Searching by name pulls up a person’s current license category, when it expires, which insurer sponsors them, and whether any conditions have been attached to their license, information that would otherwise require directly asking the person and simply trusting their answer. Given that Manitoba treats unlicensed insurance activity as a genuine offence rather than a minor technicality, running this check before signing anything, particularly with someone you haven’t worked with before, costs nothing and protects you directly.
What the ICM Search Actually Tells You
Beyond simply confirming someone is licensed at all, the search results reveal the specific category of license they hold, since Manitoba’s licensing structure distinguishes between different classes of insurance activity rather than issuing one blanket credential covering everything. Knowing which category applies tells you whether the person in front of you is actually authorized to sell the specific type of coverage you need, home, auto, life, commercial, or another class entirely, rather than assuming a general “insurance license” covers every product line. The tool also shows which insurer or agency the individual is affiliated with, useful context for understanding whether you’re speaking with an independent broker representing multiple insurers or an agent working exclusively for one company.
Wawanesa: Winnipeg’s Own National Insurer
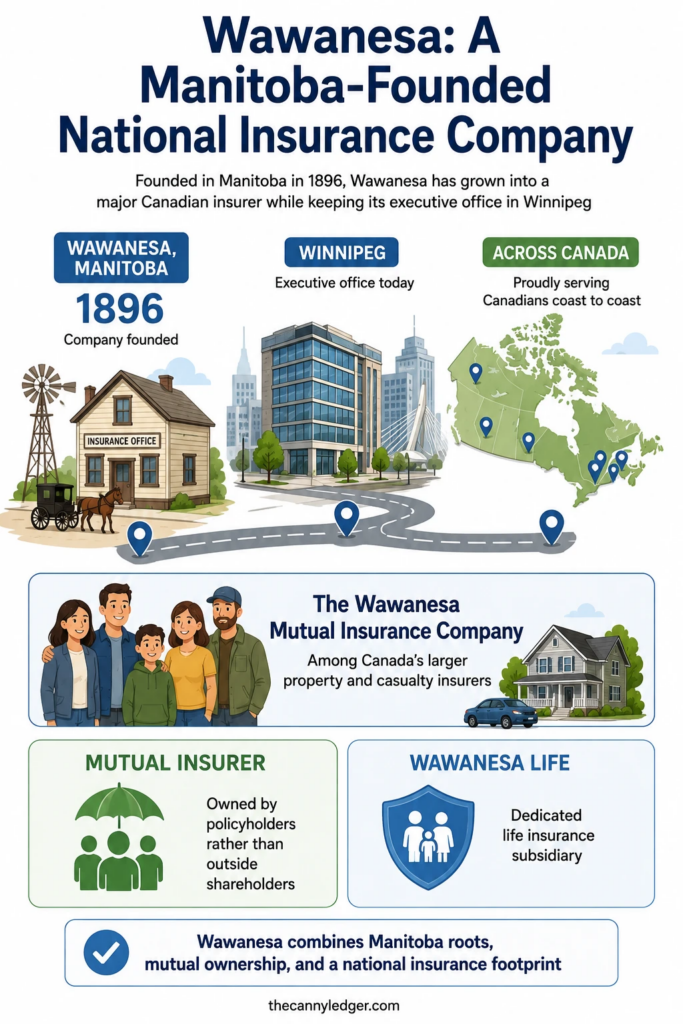
Wawanesa, officially The Wawanesa Mutual Insurance Company, ranks among Canada’s ten largest property and casualty insurers, and while its founding roots trace to the small town of Wawanesa, Manitoba in 1896, its executive office sits in downtown Winnipeg today. As a mutual company, Wawanesa is owned by its policyholders rather than shareholders, a structural difference from publicly traded insurers that shapes how profits and priorities flow through the organization. Beyond property and casualty coverage, the company operates Wawanesa Life as a dedicated life insurance subsidiary, and our guide to life insurance in Winnipeg covers that side of the business in more depth for anyone specifically comparing term versus whole life options.
Red River Mutual: Manitoba-Rooted, Broker-Distributed
Red River Mutual traces its founding back to 1875, making it one of the older continuously operating insurers in the province, and while its headquarters sit in Altona, Manitoba, it maintains a regional office in Winnipeg and works through a network of independent brokers across the province rather than selling directly to consumers. As a mutual company owned by more than 75,000 policyholders, Red River Mutual covers home, farm, and business insurance, and its farm-specific coverage sits alongside the broader agricultural insurance landscape our guide to farm and agricultural insurance in Winnipeg covers in full, including how private farm coverage like this fits alongside Manitoba’s separate crop insurance system.

Mutual vs Stock Companies, and Why It’s Worth Knowing
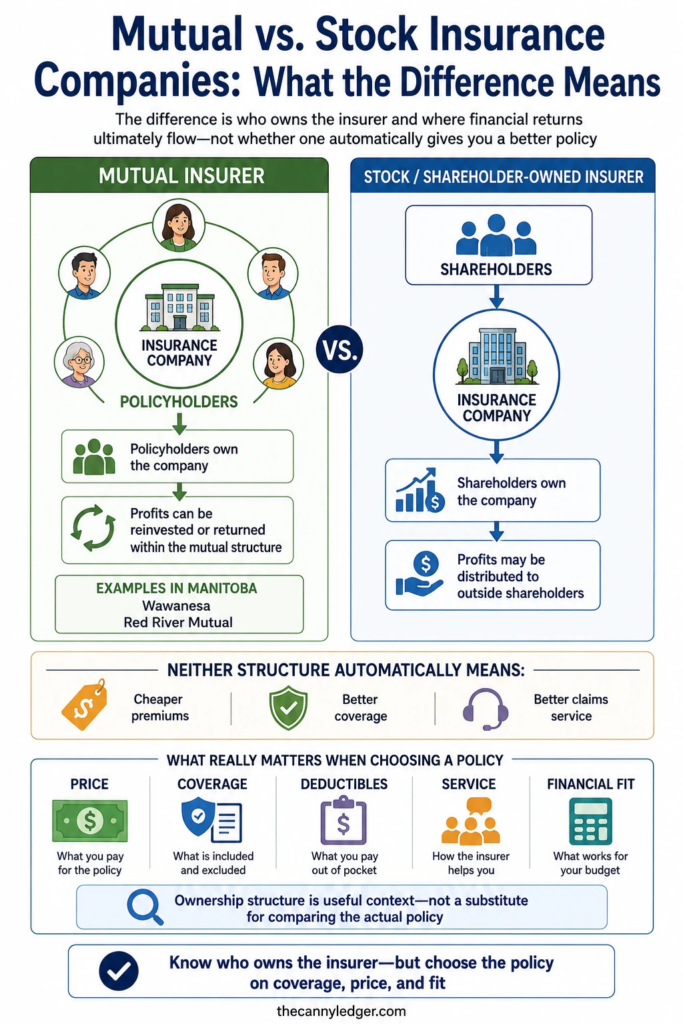
The mutual structure both Wawanesa and Red River Mutual operate under means policyholders effectively own the company, and profits generally get reinvested or returned to policyholders rather than distributed to outside shareholders the way a publicly traded, stock-based insurer would. This isn’t automatically better or worse for a specific policyholder’s rate or coverage, but it does mean a mutual insurer’s incentive structure points differently than a shareholder-owned one, worth knowing when comparing quotes between a Manitoba-rooted mutual and a larger national or multinational stock insurer active in the same market.
Direct Writers vs Broker-Distributed Insurers
Some insurers, called direct writers, sell policies straight to consumers through their own agents or online channels without going through an independent broker at all. Others distribute exclusively or primarily through independent brokers, meaning you can’t buy a policy directly from the company itself even if you wanted to, you need to go through a broker who represents them alongside other insurers. Red River Mutual’s broker-distributed model is a clear example of this second structure, while other companies active in the Winnipeg market operate as direct writers instead. Understanding which model a specific insurer uses before you start shopping tells you whether you’ll be dealing with the company directly or need to find a broker carrying their products first.

National Insurers With a Real Winnipeg Presence
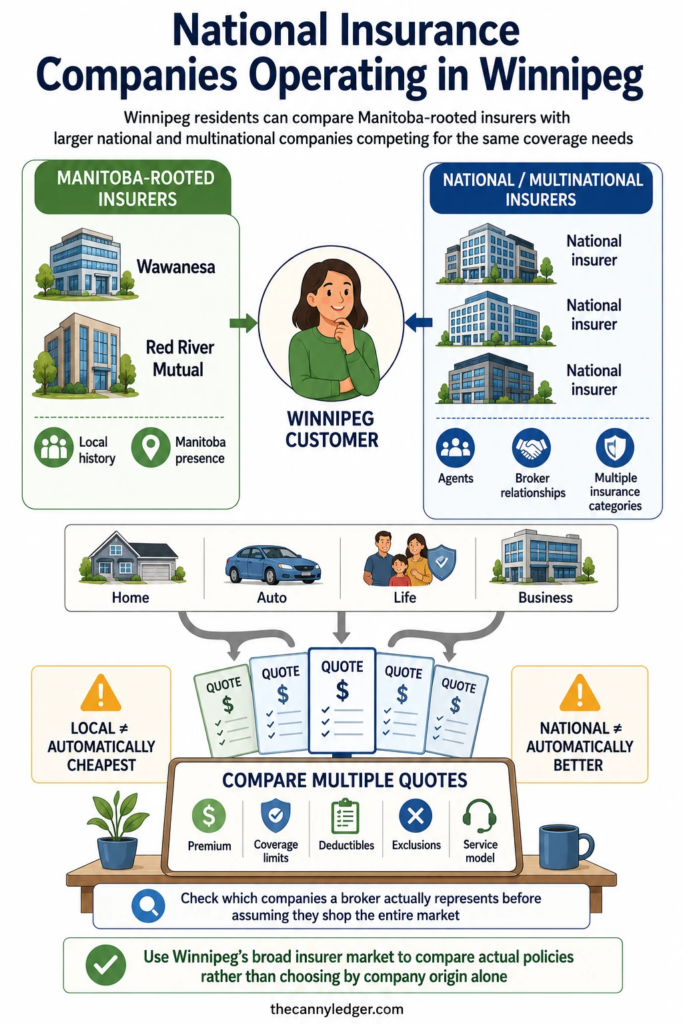
Beyond Manitoba-rooted companies, most major national insurers, including large multinational property, casualty, and life insurance companies, maintain active operations, agents, or broker relationships throughout Winnipeg, giving residents genuine choice beyond the two Manitoba-headquartered options profiled above. Our guide to small business insurance in Winnipeg touches on several of the coverage categories these national players compete in directly alongside Manitoba’s own insurers, and checking multiple quotes across both categories, Manitoba-rooted and national, before committing to any single provider remains the most reliable way to confirm you’re getting genuinely competitive pricing rather than assuming local automatically means best value.
Finding the Right Broker for Your Specific Coverage
Choosing between a direct writer and an independent broker, or between a Manitoba-rooted insurer and a larger national one, ultimately depends on what specific coverage you need and how much you value having one person compare multiple insurers on your behalf versus dealing with a single company directly. Our dedicated guide to choosing an insurance broker in Winnipeg walks through that decision process in full, covering what questions to ask and how to evaluate a broker’s fit for your specific situation once you’ve confirmed their license is genuinely valid through the ICM’s search tool.

Common Questions
Does a valid ICM license mean an agent or broker is automatically trustworthy? Not entirely, licensing confirms someone meets Manitoba’s minimum legal requirements to sell insurance and hasn’t had their license suspended or revoked, but it doesn’t guarantee they’re the best fit for your specific needs, so treating the license check as a baseline safety filter rather than a full endorsement makes sense.
Can I check a company’s overall standing, not just an individual agent’s license? The ICM’s search tool covers individual agents, brokers, and adjusters specifically, so for a company-level check, confirming the insurer itself is authorized to do business in Manitoba is a separate step, typically straightforward to confirm directly through the insurer’s own website or by asking your broker directly.
Is it normal for an insurer to only sell through brokers rather than directly to me? Yes, this is a genuinely common business model in the Canadian insurance industry, and it doesn’t reflect anything negative about the insurer, it simply means you’ll need to work through a broker carrying their products rather than approaching that specific company directly.
Verify Before You Sign Anything
Before finalizing a policy with any Winnipeg insurance company or broker, spend the two minutes it takes to run their name through the Insurance Council of Manitoba’s public search tool, confirming their license is current, their category actually covers what you’re buying, and no conditions or red flags are attached. That single check, combined with comparing at least one Manitoba-rooted option against a national alternative, is the most reliable foundation for a genuinely informed insurance decision rather than one based on trust alone.