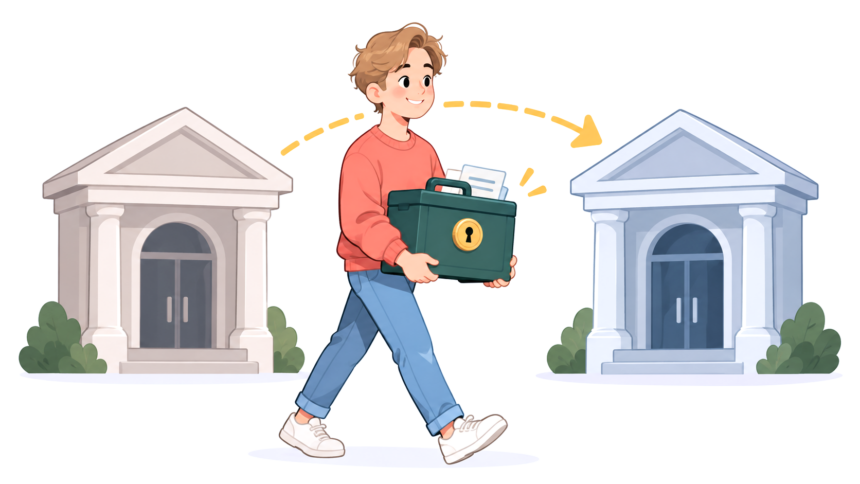
Two specific government forms, not a phone call to your bank, are what actually move a Registered Disability Savings Plan (RDSP) from one financial institution to another. There’s no button in an app that reassigns the account overnight. Behind the scenes, the old plan gets closed and a new one gets opened in its place, with the government quietly carrying over the grant history, bond history, and entitlement so none of it needs to be recreated from scratch.
- What Counts as a Transfer
- The Two Forms That Actually Do the Work
- What Has to Match at the New Institution
- What Happens to Your Grant and Bond History
- The 120 Day Clock
- If the Beneficiary Is Near or Past 59
- What It Actually Costs
- Mistakes People Commonly Make
- What to Do Next
- A Few More Questions Worth Answering
An RDSP transfer moves the entire account, all funds and all historical grant and bond information, from one issuer to a new RDSP opened for the same beneficiary at a different institution. Partial transfers aren’t allowed. The receiving institution must preserve any special terms the old plan had, and the old plan is closed once the transfer completes.
What Counts as a Transfer
A genuine RDSP transfer has a specific legal shape, and it’s worth understanding before assuming the process works like moving a TFSA between two brokerages. According to Canada.ca’s own description of the process, the new RDSP has to have the exact same beneficiary as the outgoing plan, and the financial institution holding the current account has to transfer all of the plan’s property directly to the new one. There’s no version of this where half the balance moves and half stays behind.
Because the beneficiary can only hold one RDSP at any given time, the outgoing plan gets terminated by the relinquishing institution once the funds successfully land in the new account. This isn’t a parallel account structure. It’s a full handoff, followed by the old plan ceasing to exist.
The Two Forms That Actually Do the Work
The mechanics run through two specific documents. Form EMP5611, the RDSP Transfer form, gets completed by both the relinquishing and receiving institutions and carries the technical details needed to register the new contract correctly. Form EMP5612, the Holder Consent form, is where every holder of the existing plan formally agrees to the transfer, a step that matters especially when a plan has more than one holder or when the holder situation is changing as part of the move.
Neither of these forms gets sent directly to the government. According to the official ESDC transfer video for issuers, the holder completes the relevant sections and hands them to the institution, which then handles the electronic reporting to Employment and Social Development Canada on the holder’s behalf. As the account holder, your job is filling out these two forms accurately and choosing where the new plan goes, not chasing paperwork through a government office.
What Has to Match at the New Institution
A detail that’s easy to overlook when comparing providers is that the receiving institution can’t simply offer whatever terms it normally offers. If the beneficiary’s previous plan allowed for rollovers from a deceased parent’s RRSP, a Specified Disability Savings Plan designation for shortened life expectancy, or a qualifying family member serving as holder, the new plan has to permit those same measures. A financial institution that doesn’t support one of these provisions isn’t a viable destination for a plan that already relies on it, so confirming this upfront avoids finding out partway through the process that the transfer can’t actually complete as planned.
What Happens to Your Grant and Bond History
This is the part that reassures most people once they understand it. Nothing about the grant and bond entitlement already earned gets recalculated or lost in a transfer. Employment and Social Development Canada sends the receiving institution all of the historical transactional information from the old plan once it closes, meaning the new provider has everything needed to continue managing carry-forward room and the assistance holdback amount without the family needing to reconstruct any of that history manually.
Transfers also aren’t treated as new contributions, so moving an account doesn’t touch the beneficiary’s $200,000 lifetime contribution ceiling in either direction. The lifetime total simply carries forward with the rest of the plan’s history.
The 120 Day Clock
Once a new RDSP contract is signed at the receiving institution, the Ontario Securities Commission’s investor education resource on RDSP transfers states that the actual transfer of funds has to be completed within 120 days. Miss that window, and the new RDSP is considered invalid, which is a serious enough consequence that it’s worth confirming directly with both institutions where things stand as the deadline approaches rather than assuming the paperwork is quietly moving along in the background.
If the Beneficiary Is Near or Past 59
There’s a specific rule that applies to families transferring an account for a beneficiary already receiving mandatory withdrawals. If the beneficiary was 59 or older at the start of the year the transfer happens, the old plan still has to pay out any Lifetime Disability Assistance Payments it would have paid for the rest of that year had the transfer never happened. In practice, that means switching providers mid-year doesn’t pause or skip a scheduled mandatory withdrawal, it just gets paid out by the outgoing institution before the account closes.
What It Actually Costs
Transfer fees aren’t standardized across the industry, and they can vary meaningfully between institutions. RBC, for instance, charges $150 to transfer an RDSP out to a different provider, a figure worth confirming directly with your current institution before initiating anything, since a fee that size is worth factoring into the decision alongside whatever advantage the new provider actually offers.
Mistakes People Commonly Make
The most common one is assuming a partial transfer is possible, splitting a large balance between two institutions to diversify providers. It isn’t. Every dollar and every piece of plan history moves together or not at all. The second is initiating a transfer before confirming the new institution actually supports whatever special provisions the old plan relied on, whether that’s an SDSP designation, a qualifying family member holder, or a pending rollover, since discovering a mismatch partway through can stall the process entirely. And the third is not accounting for the mandatory LDAP payout rule when a beneficiary is close to 59, which can create a smaller-than-expected balance actually moving to the new provider if a scheduled payment comes due during the transfer window.
What to Do Next
Before initiating anything, ask the prospective new institution directly whether they support every special provision currently attached to the self-directed or managed plan structure, not just whether they offer RDSPs generally. Once you’ve confirmed that, request the transfer paperwork from the new institution, since the process typically starts there rather than with the outgoing provider. And if the beneficiary is approaching age 59, confirm with the current provider exactly how any scheduled LDAP payments will be handled during the transfer window before signing anything at the new institution.
A Few More Questions Worth Answering
Can I split my RDSP between two institutions instead of transferring the whole thing? No. A full transfer of every dollar and all associated plan history is the only option, and the beneficiary can only hold one RDSP at any given time regardless of how many institutions are involved.
Does a transfer count as a new contribution toward the lifetime limit? No. Transferred funds are not treated as a fresh contribution, so a transfer has no effect on how much of the $200,000 lifetime ceiling has already been used.
Will I lose access to carry-forward room I’ve already banked? No. Employment and Social Development Canada provides the receiving institution with the complete historical record from the old plan, so carry-forward entitlement and grant history continue exactly as they were before the move.