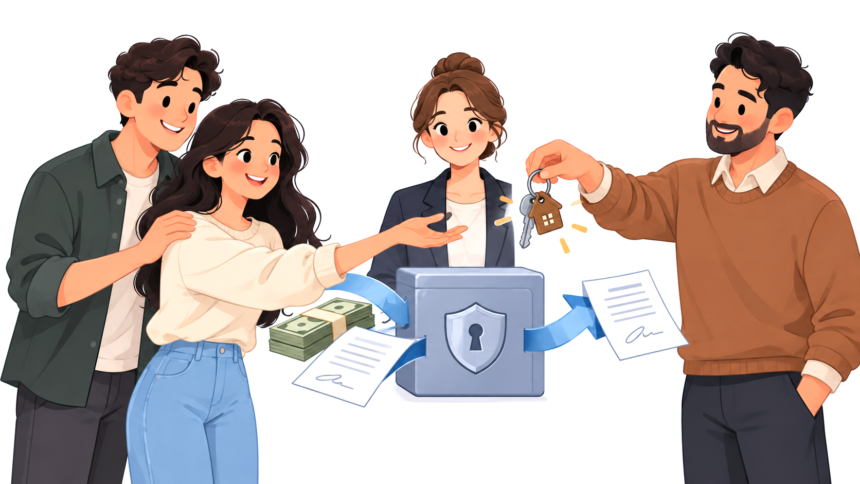
Mortgage closing day is when the legal and financial pieces of your home purchase are completed. Money changes hands, ownership is transferred, and, once the transaction is completed, you can take possession of the property. On mortgage closing day in Canada, your lender advances the mortgage funds to your lawyer or notary, you provide the remaining money required from you, and your lawyer or notary completes the transfer to the seller. The property is registered in your name, and you receive the keys once the transaction closes.
- Your Mortgage Funds Are Advanced
- You Provide the Remaining Money Required to Close
- Your Lawyer or Notary Completes the Financial Adjustments
- The Seller Is Paid and Ownership Is Transferred
- You Get the Keys After the Transaction Closes
- What Could Delay Mortgage Closing?
- What Should You Do Before Closing Day?
- Questions About Mortgage Closing Day
Your Mortgage Funds Are Advanced
Your lender does not normally hand the mortgage money directly to you. The funds are advanced to the lawyer or notary handling the transaction so they can be used to complete the purchase. CMHC’s homebuying process places this transfer of funds among the final steps in taking legal possession of a home.
The amount advanced should reflect the financing that was finalized before closing. For mortgages from federally regulated financial institutions, the lender must disclose information such as the principal, the date funds will be advanced, the interest rate, payment details and other applicable charges. Reviewing these mortgage details before signing gives you an opportunity to resolve discrepancies before the purchase reaches its final stage.
You Provide the Remaining Money Required to Close
The mortgage does not cover everything you may owe. Your lawyer or notary also needs the portion of the purchase price that must come from you, taking into account money such as the deposit you already paid.
You will also need to cover the closing expenses applicable to the transaction. Legal fees, property tax adjustments, title insurance and other upfront expenses can form part of the broader mortgage closing costs in Canada. Federal guidance recommends budgeting approximately 1.5% to 4% of the purchase price for closing costs, although the actual amount depends on the transaction.
This money should be arranged before closing rather than treated as part of the mortgage advance. Although some mortgage-related expenses can be financed in particular circumstances, you generally should not assume that you can roll your closing costs into the mortgage.
Your Lawyer or Notary Completes the Financial Adjustments
The amount needed to close may differ from a simple calculation of purchase price minus mortgage and deposit. Certain property expenses can require adjustments between you and the seller.
Suppose the seller has already paid property taxes covering a period after you become the owner. Your share can be accounted for in the closing adjustments so that the seller is reimbursed for the portion relating to your ownership period. Property tax adjustments are among the closing expenses identified in federal home-buying guidance.
These adjustments are transaction-specific. Your lawyer or notary calculates the amount that must ultimately be settled rather than leaving the buyer and seller to work it out after possession changes.
The Seller Is Paid and Ownership Is Transferred
Once the required funds and documents are in place, your lawyer or notary completes the transfer. The purchase money is paid to the seller as required, and the property is registered in your name through the applicable provincial or territorial land registration system. CMHC describes registration in the buyer’s name as one of the central events of closing day.
The precise registration process is not identical across Canada because property registration falls under provincial and territorial systems. The federal explanation of how land title registries handle mortgage interests confirms that these offices maintain official property titles and process changes affecting them.
You Get the Keys After the Transaction Closes
Getting the keys is the visible part of closing day, but it comes after the legal and financial work has been completed. CMHC describes closing day as the point when the buyer takes legal possession and receives the keys after the lawyer or notary has paid the seller and registered the home in the buyer’s name.
That means a scheduled closing date does not necessarily guarantee that you will have the keys first thing in the morning. The transaction still needs to reach completion.
For that reason, avoid making plans that depend on receiving possession at a particular hour unless the professionals handling your purchase have confirmed the timing. Closing day is better understood as a process that finishes with possession, not simply an appointment to collect keys.
What Could Delay Mortgage Closing?
Missing money, unresolved documentation or a financing problem can prevent the transaction from being completed as expected. A mortgage preapproval by itself does not guarantee final mortgage approval, and a lender can still decline financing after preapproval if its requirements are not satisfied.
Problems at this stage can be serious because you already have a purchase agreement with a scheduled completion date. The consequences depend on the agreement, the reason for the delay and applicable provincial law, so legal advice may be necessary when a transaction cannot close as planned.
The financing side of that situation is covered separately in what can happen when a mortgage falls through on closing day.
What Should You Do Before Closing Day?
Have the required funds available in the form and by the deadline your lawyer or notary specifies. Confirm that requested identification and documents have been provided, and review the mortgage information supplied by your lender before signing anything you do not understand.
It is also sensible to avoid making significant financial changes while the mortgage is being finalized. A preapproval is not a final approval, and lenders consider your income, assets, debts and other financial obligations when assessing a mortgage application.
Once your lawyer or notary confirms that the transaction has closed, ownership has been transferred and possession is available, the purchase has reached the point you have been preparing for: the home is legally yours.
Questions About Mortgage Closing Day
Do you meet the seller on closing day?
Not necessarily. Your lawyer or notary handles the legal and financial completion of the transaction, so closing does not require the buyer and seller to personally exchange the purchase money.
Does your first mortgage payment happen on closing day?
The mortgage funds are advanced for the purchase on closing day, but your regular payment schedule follows the payment dates established in your mortgage agreement. Federally regulated lenders must disclose the payment amount, due date and frequency.
Can closing happen without a lawyer or notary?
The process depends on the province or territory, but buyers commonly use a lawyer or notary to complete the legal transfer. Federal guidance specifically directs homebuyers whose offer has been accepted to hire a lawyer or notary to transfer the home into their name.
Can you move in before the mortgage closes?
Possession normally follows completion of the purchase according to the agreement. Do not assume you can occupy the property before your lawyer, notary or other appropriate professional confirms that possession is available.