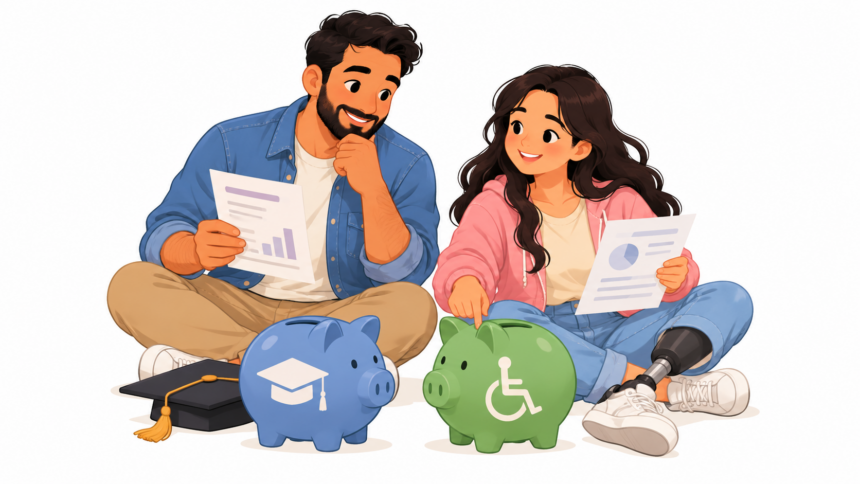
A child diagnosed with a qualifying disability early in life can have both a Registered Education Savings Plan (RESP) and a Registered Disability Savings Plan (RDSP) open at the same time, funded by the same parents, without either account interfering with the other. There’s even a bridge between them, since an RESP’s unused investment growth can roll over into that same child’s RDSP if education never ends up happening. The bridge only runs one direction. Nothing moves from an RDSP back into an RESP, since the two accounts were built around fundamentally different assumptions about what the beneficiary’s future looks like.
Understanding those different assumptions is really the whole comparison, since an RESP and an RDSP aren’t competing options for the same goal the way a TFSA and an RRSP sometimes are. They’re built for different populations, with different government incentives, and different consequences if life doesn’t go the way either account expects.
Who Actually Qualifies
An RESP beneficiary just needs a Social Insurance Number and Canadian residency, nothing more. Any child, or even an adult in some cases, can be named to one. An RDSP beneficiary needs all of that plus approval for the Disability Tax Credit, a specific, documented medical qualification that an RESP has no equivalent of. This single difference explains almost everything else that follows. An RESP is built for the general population of Canadian children. An RDSP is built for a narrower group defined by a specific medical and legal test.
One Beneficiary Only, Always
A family RESP can pool several siblings under a single plan, sharing contribution room and letting CESG entitlements move between them freely. An RDSP has no equivalent structure at all. Every RDSP has exactly one beneficiary, permanently, with no family-plan option and no mechanism for pooling multiple children’s disability savings into a shared account. A family with more than one child who qualifies for the DTC needs a completely separate RDSP for each one, run entirely independently of each other.
How Much Government Money Is Actually on the Table
An RESP beneficiary can attract up to $7,200 in Canada Education Savings Grant money over a lifetime, on top of a $50,000 contribution ceiling. An RDSP beneficiary is looking at a substantially larger program. The Canada Disability Savings Grant alone maxes out at $70,000, and the Canada Disability Savings Bond adds another $20,000 for lower-income households with no contribution required at all, for a combined $90,000 in possible government money against a $200,000 lifetime contribution limit, four times the RESP’s ceiling. The RDSP program was built around a much longer time horizon and a much larger total commitment than the RESP was ever designed for.
The Income Sensitivity Built Into Each Grant
Both grants scale with family income, but nowhere near the same degree. The CESG runs at a flat 20 percent for every income level, with a modest additional 10 or 20 percent layered on top of the first $500 for lower and middle income families. The base rate barely changes based on income. The CDSG works completely differently, with a lower-income household earning 300 percent on the first $500 contributed and 200 percent on the next $1,000, collapsing to a flat 100 percent for anyone above the income threshold. That’s a difference of three to one between the top and bottom rates, far steeper than anything built into the RESP system, and it means family income genuinely changes the optimal contribution strategy for an RDSP in a way it barely does for an RESP.
What Happens if the Money’s Original Purpose Falls Through
This is where the two accounts diverge most sharply in spirit. An RESP is built around the assumption that a beneficiary will eventually pursue post-secondary education, and when that doesn’t happen, the leftover investment growth faces a real penalty, taxed at the subscriber’s marginal rate plus an additional 20 percent, unless it’s rolled into an RRSP or an RDSP under specific conditions. An RDSP never makes that same assumption in the first place. There’s no designated purpose a beneficiary has to fulfill to avoid a penalty, since the account was never restricted to funding any particular life outcome beyond long-term financial security generally. Money comes out, subject to its own withdrawal formula and repayment rules, and gets used for whatever the beneficiary needs, without a parallel version of the RESP’s AIP penalty hanging over it.
The One-Way Bridge Between Them
The connection between the two flows in a single direction because of how each account’s purpose is defined. An RESP’s unused growth can become part of an RDSP for a beneficiary who qualifies for the DTC, since that money simply shifts from one government-incentivized savings goal to another. There’s no equivalent path moving RDSP money into an RESP, since doing so would mean redirecting money that already avoided the education-specific structure back into an account built entirely around that structure. If a family is holding both accounts for the same child, this asymmetry is worth knowing before assuming money can be shuffled freely between them as circumstances change.
Deciding Which One, or Both, Fits
If a child qualifies for the Disability Tax Credit, opening an RDSP alongside an existing RESP costs nothing and captures an entirely separate pool of government matching that has no relationship to whether that same child eventually pursues post-secondary education. The two accounts don’t compete for the same contribution dollars in any meaningful way, since RESP contribution room and RDSP contribution room are entirely separate limits governed by entirely separate programs. Fund the one tied to the more time-sensitive deadline first, generally the RESP given its narrower grant-eligible window, and treat the RDSP as the longer-horizon account it’s actually built to be, since its own grant and bond deadlines run over a decade further into the beneficiary’s life than anything the RESP offers.