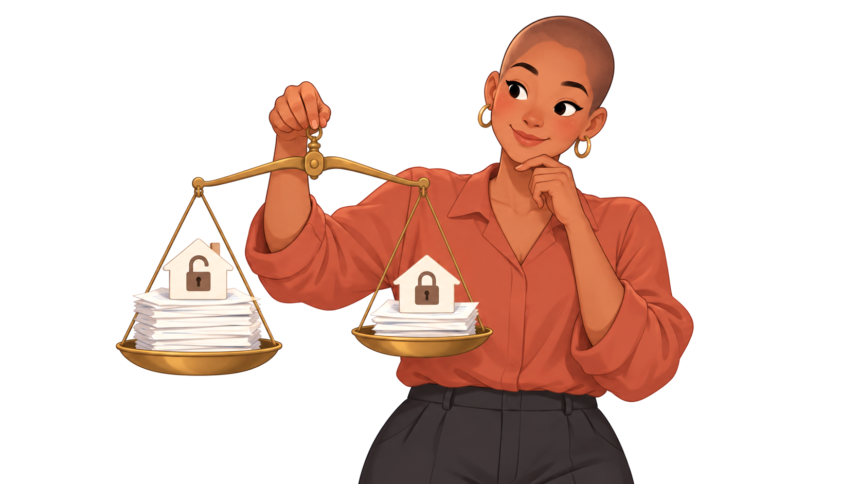
The interest-rate difference between open and closed mortgages is not arbitrary. An open mortgage gives you considerably more freedom to repay the debt before the term ends, while a closed mortgage places limits on that flexibility. Open mortgage rates are typically higher than closed mortgage rates with similar terms in Canada. The higher rate reflects the additional flexibility of an open mortgage, which allows extra payments or full repayment without a prepayment penalty. Closed mortgages generally trade some of that flexibility for a lower rate.
- Why Open Mortgage Rates Are Higher
- Why Closed Mortgage Rates Are Usually Lower
- A Lower Rate Does Not Automatically Mean a Lower Overall Cost
- How Much Can a Higher Mortgage Rate Affect Your Cost?
- When Paying the Higher Open Mortgage Rate Can Make Sense
- What to Compare Beyond the Advertised Rate
- Questions About Open and Closed Mortgage Rates
Why Open Mortgage Rates Are Higher
With an open mortgage, you can put extra money toward the principal without a prepayment penalty. You can also repay the entire balance before maturity without that charge. Mortgage prepayment rules. That freedom makes the mortgage less restrictive for you, but it also means the lender has less certainty about how long the loan will remain outstanding. Open mortgages are therefore typically priced at higher interest rates than closed mortgages with comparable terms.
The size of the difference is not fixed across Canada. Mortgage rates vary by lender, term, interest type, credit history and other factors. Looking at current open mortgage rates in Canada is more useful than assuming there is a standard premium that every lender charges for an open mortgage.
Why Closed Mortgage Rates Are Usually Lower
A closed mortgage limits how much additional principal you can repay during the term without triggering a penalty. The contract may still provide prepayment privileges, such as permitted lump-sum payments or increases to your regular payments. These privileges vary by lender.
Accepting those restrictions generally comes with a rate advantage. Closed mortgages typically have lower rates than open mortgages with similar terms.
That can make a closed mortgage less expensive when you expect to keep it until maturity and its prepayment privileges already accommodate any extra payments you intend to make. Current closed mortgage rates in Canada provide the appropriate comparison rather than comparing products with different terms or rate structures.
A Lower Rate Does Not Automatically Mean a Lower Overall Cost
Interest is only one potential cost of the mortgage contract. A closed mortgage can become more expensive than expected if you later need to leave it early.
Breaking a closed mortgage normally results in a prepayment penalty, and the charge can reach thousands of dollars. An open mortgage can be broken without a prepayment penalty. Other costs may still arise when changing mortgages. Costs of breaking a mortgage contract. This creates the central trade-off between the two rate types. The closed mortgage offers the rate advantage upfront, while the open mortgage reduces the financial restriction attached to early repayment.
We would compare those features based on what you realistically expect to do, not on the advertised rate alone. The difference between open and closed mortgages matters most when there is a credible chance your plans will change before maturity.
How Much Can a Higher Mortgage Rate Affect Your Cost?
Even a relatively small rate difference matters because mortgage interest applies to a large outstanding balance. A higher interest rate increases the amount you pay to borrow, while the mortgage term affects how long the contractual rate and other conditions apply.
For that reason, comparing an open and closed mortgage requires matching similar products. A one-year open mortgage should not be compared casually with a five-year closed mortgage and attributed entirely to the open-or-closed designation. Term length itself can affect the interest rate. How mortgage terms affect interest costs
The same principle applies to fixed and variable rates. Open versus closed describes prepayment flexibility, whereas fixed versus variable describes how the interest rate behaves during the term. Mixing those features can produce a misleading rate comparison.
When Paying the Higher Open Mortgage Rate Can Make Sense
A higher open rate can be reasonable when unrestricted repayment solves a problem you genuinely expect to have. You might anticipate selling the property soon, paying off the mortgage in the near future or receiving money that you intend to put toward the balance. These are situations where an open mortgage’s additional flexibility can have practical value.
The calculation changes when those events are unlikely. A closed mortgage may already allow substantial additional payments through its prepayment privileges. Ways to make additional mortgage payments Paying a higher rate for unlimited flexibility becomes harder to justify when you expect to use only a fraction of what the closed contract already permits.
That is the question worth answering before accepting the rate premium: how likely are you to use the feature you are paying more to receive? The circumstances covered by when to consider an open mortgage can help separate a genuine need for flexibility from a feature that merely sounds reassuring.
What to Compare Beyond the Advertised Rate
Compare mortgages with the same or similar term length and interest-rate structure first. Then check the prepayment privileges, prepayment penalties and other contract conditions. Federally regulated lenders must disclose whether a mortgage is open or closed, along with key information such as its term and annual interest rate. Mortgage disclosure requirements
A closed mortgage with a lower rate and sufficient prepayment privileges may offer everything you need. An open mortgage can justify its higher rate when avoiding repayment restrictions has a realistic financial purpose. Comparing both the borrowing cost and the contract conditions gives you a much more meaningful comparison than choosing whichever mortgage displays the lowest percentage.
Questions About Open and Closed Mortgage Rates
Are open mortgage rates always higher than closed mortgage rates?
Open mortgages typically have higher rates than closed mortgages with similar terms, but actual offers depend on the lender and characteristics of the mortgage. Compare current products on equivalent terms rather than treating the relationship as an absolute rule.
Can your credit history affect the open or closed mortgage rate you receive?
Your credit history is one factor lenders may use when determining the interest rate offered on a mortgage. A stronger credit history may help you qualify for a lower rate.
Does choosing a shorter mortgage term guarantee a lower rate?
Not necessarily. Lenders may offer different rates for different term lengths, and shorter terms often have lower rates, but that is not always the case.