Most people trying to work out their own CDIC coverage end up doing the same thing, mentally adding up every account balance at a bank into one number and comparing it against $100,000. That single-number approach is wrong often enough to matter, since CDIC doesn’t insure a person, it insures specific categories of deposit separately, and the difference between those two ways of counting can be the entire gap between feeling protected and actually being protected. The calculator below does the category math directly. The explanation underneath it covers exactly what that math is doing and where its limits are.
Use the calculator to enter each deposit by institution and category, and it totals your coverage the way CDIC actually calculates it, up to $100,000 per institution per category, rather than treating everything at one bank as a single combined balance. The sections below explain the specific rules the tool applies, and the situations it deliberately doesn’t try to handle, since those need a closer look at your specific circumstances instead of a general calculator.
How to Actually Use This
Add one row for every deposit that sits in a distinct category or a different institution, a chequing account, a savings account, a GIC, a TFSA, an RRSP, and so on. Two accounts held in one name at the same bank, a chequing account and a savings account for instance, belong in the same category and should either be entered as separate rows under the same institution and category, since the calculator adds them together automatically, or combined into a single row if that’s simpler. The calculator groups everything by institution and category together, applies the $100,000 ceiling to each group, and shows both the fully protected total and anything sitting above that line.
The Category Rule the Calculator Is Actually Running
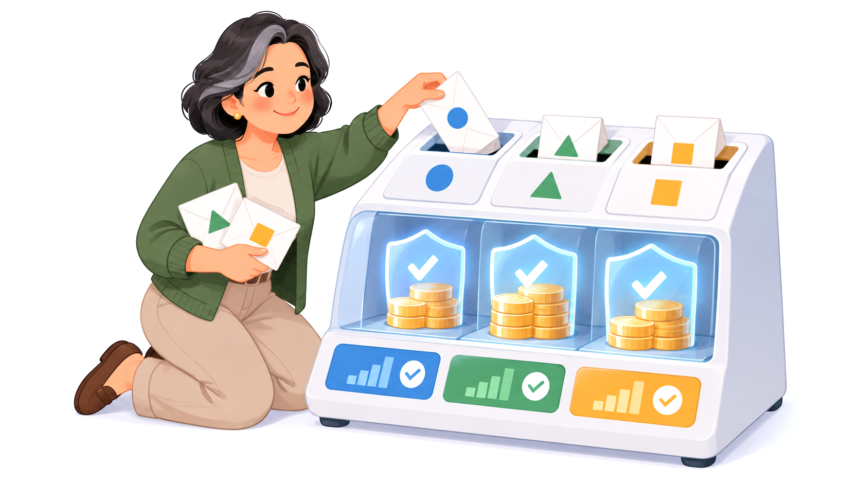
CDIC treats nine separate categories as independent from each other at every member institution, deposits held in one name, joint deposits, RRSPs, RRIFs, TFSAs, RESPs, RDSPs, FHSAs, and deposits held in trust, a structure CDIC’s own coverage page lays out directly. Each category gets its own $100,000 ceiling, which is why someone with $90,000 in a personal chequing account and $80,000 in a TFSA at the same bank has both amounts fully insured rather than a combined $170,000 competing for a single limit. The calculator mirrors this directly, grouping by institution and category rather than by institution alone, which is the specific point where a manual mental calculation most often goes wrong.
Why the Same Bank Can Show Up More Than Once
Entering the same institution name across several rows with different categories is intentional, not a workaround. A depositor with money in a personal account, a joint account with a spouse, and a TFSA all at one bank should see three separate lines in the results, each carrying its own $100,000 ceiling, rather than one combined total, exactly the multiplication effect the Financial Consumer Agency of Canada describes when explaining how CDIC categories work in practice. This is also why spreading a large balance across more than one CDIC member institution actually multiplies protection rather than just spreading risk around, since each institution runs the same category math independently of every other one.
What the Calculator Deliberately Doesn’t Try to Handle
A few real situations need more judgment than a general calculator can apply, and it’s worth naming them directly rather than pretending the tool covers everything. Deposits held in trust for a specific named beneficiary can be insured separately per beneficiary rather than as one combined trust category, which this calculator doesn’t attempt to model since it depends on proper beneficiary disclosure to the institution. Coverage that stacks across affiliated institutions within the same banking group, a detail that applies more often than most depositors realize, also isn’t captured here, since it depends on which specific institutions are actually affiliated. And credit unions generally fall outside CDIC entirely, covered instead by a provincial insurer with its own rules and, in several provinces, no dollar ceiling at all, which makes running credit union deposits through a CDIC-based calculator the wrong tool for that specific situation.
A Worked Example Using the Tool
Picture someone with $60,000 in a personal chequing account, $45,000 in a joint account with a partner, and $120,000 in an RRSP, all at the same bank. Entered as three rows, the calculator shows the chequing and joint categories fully insured at their actual balances, since both sit under $100,000, while the RRSP row shows $100,000 insured and $20,000 exposed, since that category’s balance crosses the ceiling on its own. The total insured amount comes to $205,000 against a total exposed amount of $20,000, a distinction a single combined-balance calculation of $225,000 against one $100,000 limit would never have surfaced correctly, the same category logic covered in more depth when comparing CDIC against Assuris for an entirely different kind of product.
What to Do With an Exposed Amount
If the calculator shows a real exposed balance in any category, the fix is usually one of two things. Move the excess to a different CDIC member institution, which restarts the $100,000 ceiling for that same category at the new bank, the same principle CDIC’s own coverage page illustrates with a depositor whose balance is protected separately at two different member institutions, or split the balance across an actually distinct category at the same institution if one legitimately applies, rather than assuming the money has to stay concentrated where it currently sits. For GICs and savings balances specifically, comparing rates across a couple of member institutions at the same time as addressing a coverage gap is worth doing together rather than as two separate errands.
Frequently Asked Questions
Does the calculator account for interest that accrues after I enter a balance? No, it works from whatever balance you enter at the time, so it’s worth updating the numbers periodically if a GIC or savings balance is growing meaningfully through accrued interest, since CDIC coverage includes both principal and any credited interest combined.
Should I include mutual funds or investment holdings in this calculator? No. The calculator is built specifically around eligible deposits, and investment products like mutual funds, stocks, and ETFs aren’t CDIC-insured deposits at all, so including them here would produce a misleading result.
Does this calculator work for joint accounts with more than two owners? Yes, a joint deposit is treated as its own category regardless of how many people share ownership, so a joint account with three or four names still gets entered as a single row under the joint deposits category.
Can I use this to check coverage on a credit union account? Not accurately, since most credit unions fall under provincial deposit insurance rather than CDIC, with different categories and, in several provinces, no dollar limit at all, so a credit union balance needs to be checked against that province’s specific rules instead of this tool.