Seeing Canada Pension Plan (CPP) contributions on a T4 does not tell you exactly how they will be treated on your tax return. Since the CPP enhancement began, employee contributions have effectively been divided into two tax treatments. Part qualifies for a non-refundable tax credit, while the enhanced portion qualifies for an income deduction.
- Why CPP Contributions Get Two Different Tax Treatments
- How the CPP Tax Credit Works
- How the CPP Tax Deduction Works
- Where the CPP Credit and Deduction Appear on Your T4 and Tax Return
- How CPP Tax Treatment Works for Self-Employed Canadians
- What Happens If You Overpay CPP?
- CPP Contributions and CPP Benefits Are Taxed Differently
- Other Questions About CPP Tax Credits and Deductions
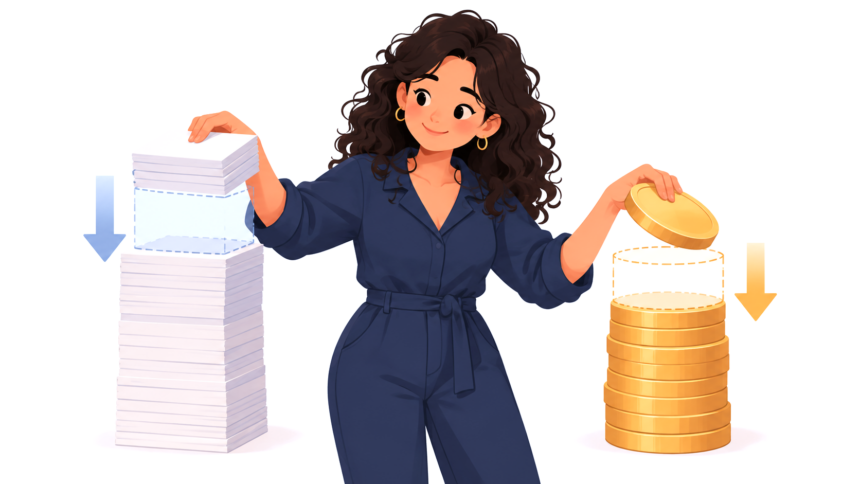
The base portion of your CPP contributions qualifies for a non-refundable tax credit. The first additional CPP contribution and CPP2 contribution are tax-deductible. A credit reduces tax payable, while a deduction reduces the income on which your tax is calculated. Self-employed Canadians have additional rules because they pay both the employee and employer portions themselves.
Why CPP Contributions Get Two Different Tax Treatments
Before the CPP enhancement, employee CPP contributions were based on the original CPP rate. The enhancement introduced additional contributions beginning in 2019, followed by CPP2 in 2024. Those enhanced contributions receive different tax treatment from the base contribution.
For employees in 2026, the regular 5.95% CPP contribution rate consists of a 4.95% base contribution and a 1% first additional contribution. The base portion qualifies for the non-refundable CPP tax credit. The 1% first additional portion qualifies for a deduction instead. If your 2026 earnings also enter the CPP2 range between the $74,600 Year’s Maximum Pensionable Earnings (YMPE) and the $85,000 Year’s Additional Maximum Pensionable Earnings (YAMPE), your employee CPP2 contributions are also deductible. The 2026 CPP rates and earnings limits separate these components even though they all form part of CPP.
This split is easy to miss because an employee’s base and first additional CPP contributions are combined in box 16 of the T4. CPP2 has its own box 16A. You do not need to guess how much of box 16 belongs to the credit and how much belongs to the deduction. Schedule 8 calculates the applicable amounts.
How the CPP Tax Credit Works
The base portion of CPP contributions made through employment qualifies for a non-refundable tax credit. For employees, the calculated base contribution is claimed on line 30800 of the federal income tax return. A corresponding provincial or territorial non-refundable credit is also available through the applicable provincial or territorial tax calculation.
A non-refundable credit reduces income tax payable rather than reducing taxable income. It can reduce your tax to zero, but an unused portion of a non-refundable credit does not create a refund by itself. This differs from a deduction, which is applied earlier when taxable income is calculated.
For 2026, the employee’s maximum base CPP contribution is $3,519.45, based on the 4.95% base rate and 2026 pensionable earnings limits. That figure should not be confused with the $4,230.45 maximum regular employee CPP contribution, which includes both the base and first additional portions. The regular CPP contribution calculation explains how the $3,500 basic exemption and YMPE affect the amount deducted from employment income.
How the CPP Tax Deduction Works
The enhanced portion of CPP contributions receives a deduction rather than a non-refundable credit. For an employee in 2026, this includes the 1% first additional contribution and any 4% CPP2 contribution made on earnings within the second earnings range.
The deductible enhanced CPP amount is claimed on line 22215 of the federal return. Your first additional contribution can reach $711 in 2026. If you earn enough to make the maximum CPP2 contribution, another $416 in 2026 can fall into the deductible enhanced contribution amount. The CPP2 maximum depends on earnings between the YMPE and YAMPE rather than earnings below the regular CPP ceiling.
A deduction lowers taxable income. Its actual tax value therefore depends partly on your marginal tax rate and other circumstances. We think this is a more useful way to understand the CPP deduction than treating it as money you automatically receive back. A $500 deduction does not mean a $500 tax refund. It means $500 is deducted in calculating taxable income.
Where the CPP Credit and Deduction Appear on Your T4 and Tax Return
An employee’s T4 generally provides the contribution information needed for the calculation. Box 16 reports employee CPP contributions covering the base and first additional components. Box 16A reports second additional CPP contributions, or CPP2. Box 26 shows the pensionable earnings used for CPP purposes.
Those boxes do not mean you simply copy the full box 16 amount onto one tax-return line. Schedule 8, Canada Pension Plan Contributions and Overpayment, separates the contributions according to their tax treatment. The base portion goes toward the line 30800 credit, while the enhanced portion is used for the line 22215 deduction.
Tax software normally performs these calculations after you enter or import your T4 information. The split becomes more noticeable when completing a paper return because Schedule 8 shows how the amounts are separated. This is one reason we would avoid manually treating every dollar shown in box 16 as either entirely a credit or entirely a deduction.
How CPP Tax Treatment Works for Self-Employed Canadians
Self-employed Canadians pay both the employee and employer shares of CPP, so their tax treatment is more involved. In 2026, the combined regular CPP contribution rate for self-employed workers is 11.90%, with a maximum regular contribution of $8,460.90. The self-employed CPP2 rate is 8%, with a 2026 maximum of $832.
The tax system separates those contributions rather than giving the entire payment one treatment. The portion corresponding to the employee’s base contribution can generate a non-refundable tax credit, while the employer-equivalent portion can be deducted. The enhanced portions are also deductible. The calculation is completed through Schedule 8 and the relevant lines of the income tax return.
That difference matters when comparing an employee’s paycheque with the CPP bill faced by someone running a business. A self-employed worker pays more directly because there is no employer paying the other half, but the tax return accounts for that employer-equivalent portion through deductions. The contribution mechanics are covered in more detail in how CPP works for self-employed Canadians.
What Happens If You Overpay CPP?
Paying CPP through more than one employer can sometimes result in total deductions exceeding the amount ultimately required for the year. The same can happen in other situations where CPP contributions need to be prorated.
When an overpayment exists, Schedule 8 calculates it and the refundable amount can be claimed on line 44800 of the federal return. An overpayment is different from the CPP tax credit or enhanced CPP deduction. The credit and deduction provide tax treatment for valid contributions, while an overpayment calculation returns CPP that you were not required to contribute.
This is particularly worth checking when you changed jobs during the year and both employers deducted CPP independently. Each employer generally calculates payroll deductions based on the employment it provides, while your tax return reconciles your overall annual CPP position.
CPP Contributions and CPP Benefits Are Taxed Differently
The tax treatment of contributions should not be confused with the tax treatment of the pension you eventually receive. Contributions made while working can generate credits and deductions under the rules above. CPP retirement benefits received later are taxable income.
So there is no single rule that says “CPP is deductible” or “CPP is a tax credit.” The answer depends on which part of CPP you mean. For workers making contributions, the base and enhanced components receive different tax treatment. For retirees receiving CPP benefits, the pension itself forms part of taxable income.
When preparing your return, the practical step is to enter all T4 information accurately and let Schedule 8 or certified tax software separate the CPP components. That keeps the base credit, enhanced deduction and any CPP overpayment in their correct places.
Other Questions About CPP Tax Credits and Deductions
Can you choose between claiming the CPP credit and the CPP deduction?
No. The tax treatment follows the type of CPP contribution. The base employee contribution qualifies for the non-refundable credit, while enhanced contributions are deductible. You cannot move an amount from one category to the other simply because one treatment would be more valuable to you.
Do employer CPP contributions give employees another tax credit?
No. An employee does not claim the employer’s CPP contribution as a personal tax credit. The employer pays its required share separately. The employee’s return deals with the employee contributions reported on the applicable T4 boxes.
What if you worked in Quebec and another province during the same year?
CPP and the Quebec Pension Plan (QPP) have separate contribution systems. Someone who contributed to both during the year may need Form RC381, Inter-Provincial Calculation for CPP and QPP Contributions and Overpayments, rather than relying only on the standard CPP calculation. The result depends on the contributions and province of residence involved.
Does claiming a CPP deduction reduce your future CPP pension?
No. Claiming the tax deduction available for enhanced CPP contributions does not erase those contributions from your CPP record. Your CPP benefit is based on the applicable contribution and earnings rules, while the deduction determines how those contributions are treated for income tax purposes.